As 2026 comes to a close, it is a good time to revisit one of the most important – and often overlooked – parts of your financial plan: your IRA beneficiary forms 2027.
Beneficiary designations can determine who receives your retirement assets, how quickly those assets transfer, and whether your wishes are carried out as intended. Even if your will or trust is up to date, your IRA beneficiary form may still control where those account assets go.
That is why year-end is an ideal time to confirm that every form is accurate, complete, and properly filed.
Why IRA Beneficiary Forms Matter
Your IRA beneficiary form is more than paperwork. It is a legal instruction to the financial institution holding your account.
If the form is missing, outdated, incomplete, or inconsistent with your estate plan, your retirement assets may not pass the way you intended. This can create unnecessary delays, family conflict, tax complications, or missed planning opportunities for the people you care about most.
For high-income families, business owners, executives, and those nearing retirement, the stakes can be especially high. Retirement accounts may represent a significant portion of your investable assets, and the transition from saving to a work-optional lifestyle requires careful coordination between financial planning, tax planning, and estate planning.
A Year-End IRA Beneficiary Checklist for IRA beneficiary forms 2027
Before the year ends, consider making the following beneficiary review part of your financial planning routine.
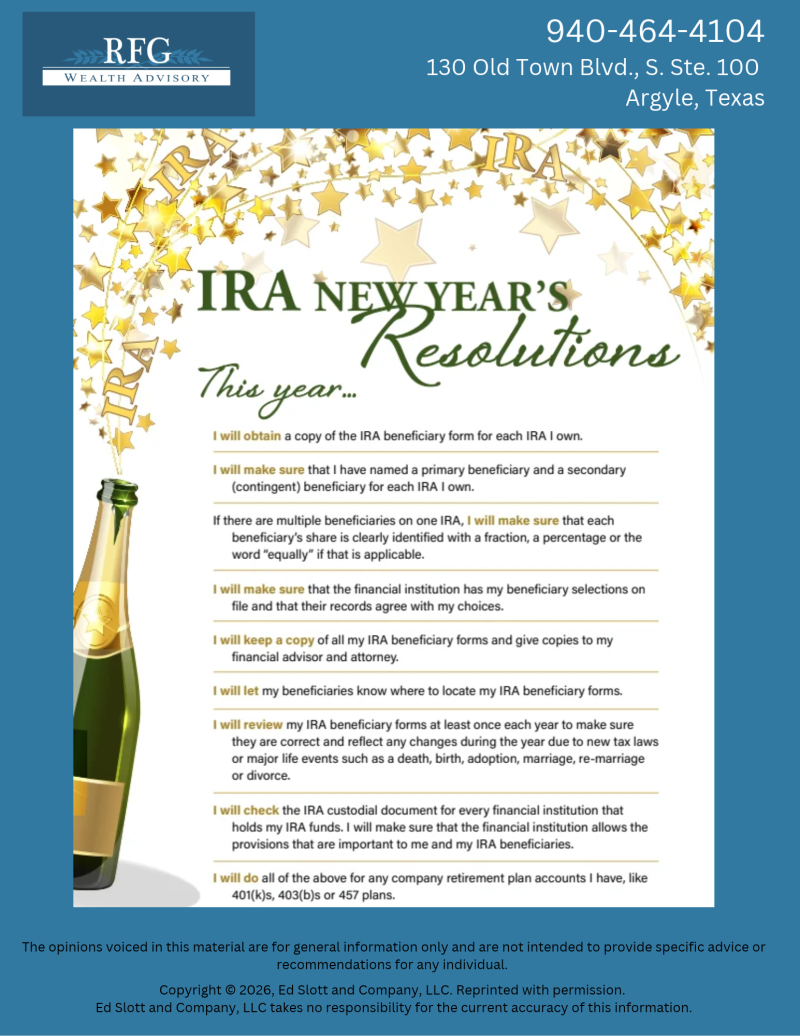
- Obtain a Copy of Every IRA Beneficiary Form
Start by gathering a copy of the beneficiary form for each IRA you own. This includes traditional IRAs, Roth IRAs, SEP IRAs, SIMPLE IRAs, and inherited IRAs, if applicable.
Do not assume that your financial institution has the correct form on file. Request a current copy and review it carefully.
- Confirm Primary and Contingent Beneficiaries
Each IRA should typically name both a primary beneficiary and a contingent beneficiary.
The primary beneficiary is first in line to inherit the account. The contingent beneficiary, sometimes called the secondary beneficiary, generally inherits if the primary beneficiary is no longer living or cannot receive the assets.
Without both levels of beneficiaries listed, your account may not transfer as smoothly as intended.
- Make Sure Multiple Beneficiaries Are Clearly Identified
If you name more than one beneficiary on the same IRA, confirm that each person or entity’s share is clearly stated.
The form should specify each beneficiary’s portion using:
- A percentage
- A fraction
- The word “equally”, if equal shares are intended
This helps reduce confusion and may prevent disputes later.
- Verify the Custodian’s Records
After reviewing your forms, confirm that the financial institution’s records match your selections.
This is an important step because your copy of the form and the custodian’s system should agree. If they do not, it may create problems when beneficiaries eventually need to claim the account.
- Keep Copies in the Right Places
Keep copies of all IRA beneficiary forms with your important financial and estate planning documents.
It is also wise to provide copies to your financial advisor and estate planning attorney. Your beneficiaries should know where the documents can be found, even if you do not share every detail of your finances with them today.
- Review Beneficiary Forms Every Year
Beneficiary forms should not be a “set it and forget it” item.
Review them at least once each year and after major life events, including:
- Marriage or remarriage
- Divorce
- Birth or adoption of a child or grandchild
- Death of a spouse, beneficiary, or family member
- Changes in tax law
- Updates to your estate plan
- Changes in family relationships or charitable intentions
A form that was correct five years ago may no longer reflect your wishes today.
- Review the IRA Custodial Document
Each financial institution has its own IRA custodial agreement. These documents can affect what options are available to your beneficiaries after they inherit the account.
Make sure the custodian allows the provisions that are important to you and your beneficiaries. This is especially important if your estate plan includes trusts, multiple beneficiaries, charitable beneficiaries, or more advanced tax planning strategies.
- Do the Same for Company Retirement Plans
This same review should apply to your company retirement plans, including 401(k), 403(b), 457, and other employer-sponsored retirement accounts.
Retirement plan beneficiary forms can be just as important as IRA beneficiary forms. If you changed jobs, retired, rolled over part of an account, or still have an old employer plan, make sure those beneficiary designations are current as well.
Beneficiary Planning Is Part of a Bigger Financial Picture
Reviewing your IRA beneficiary forms is a small year-end task that can have a major impact.
It connects directly to several areas of your overall financial life, including:
- Investment Management: Understanding how retirement assets fit into your larger portfolio
- Financial Planning: Coordinating account ownership, retirement income, and family goals
- Tax Planning: Evaluating how inherited retirement accounts may be taxed
- Estate Planning: Making sure assets pass according to your wishes
- Risk Planning: Reducing the chance of administrative mistakes, family disputes, or unintended outcomes
For families approaching retirement, beneficiary planning becomes even more important. As you move from accumulating assets to creating retirement income, your plan should reflect not only how you will use your assets, but also how those assets may transfer to the next generation or to the causes you care about.
Start 2027 With Confidence
As you prepare for the year ahead, take time to review your IRA and retirement account beneficiary forms. Confirm that your beneficiaries are named, your percentages are clear, your custodian’s records are accurate, and your documents are easy to locate.
Small planning steps today can help protect your family, reduce confusion, and support a more confident financial future.
Financial Success Doesn’t Happen by Chance.
It Starts with the RFG Blueprint.
Contact one of our RFG Wealth advisors at 940-464-4104, to discuss your IRA beneficiary planning questions. You may also schedule a free virtual consultation on our website. RFGWealthAdvisory.com/virtualconsultation/
RFG Wealth Advisory in Argyle, Texas, is an independent, fee-only Registered Investment Advisor firm that always puts our clients’ interests first. We have a transparent, simple fee structure that’s easy to understand. Call us Today!
Investment advice is offered through RFG Wealth Advisory, a Registered Investment Advisor.